What does homeowners insurance cover when your house, belongings, or finances face an unexpected loss? A standard U.S. policy protects several parts of your property and personal liability. Coverage still depends on what caused the loss and what your policy excludes. For the full picture, read Choosing the Right Homeowners Insurance Policy in Connecticut.
The most useful way to understand a policy is to separate what is damaged from why it happened. A damaged roof may be covered after a windstorm but excluded when age caused the problem. Your declarations page, limits, deductible, endorsements, and policy wording determine the final answer.
| Coverage area | What it generally protects | Common example |
|---|---|---|
| Dwelling | House and attached structures | Fire damages the kitchen |
| Other structures | Detached garage, shed, or fence | Wind damages a detached shed |
| Personal property | Furniture, clothing, electronics, and other belongings | Theft or fire damages possessions |
| Loss of use | Extra living costs after a covered loss | Hotel costs during repairs |
| Personal liability | Certain injuries or property damage involving others | A guest sues after an accident |
| Medical payments | Smaller medical expenses for injured guests | A visitor needs treatment after a fall |
Direct answer: A standard U.S. home policy usually protects the dwelling, detached structures, personal belongings, liability, and extra living costs. It may also pay certain guest medical bills after an accident. Floods, earthquakes, wear, and maintenance problems usually need separate protection or remain excluded.
Key Takeaways
- Standard policies commonly include dwelling, other structures, belongings, loss-of-use, liability, and guest medical coverage.
- Fire, wind, hail, theft, vandalism, and some sudden water damage are common covered causes.
- Flooding, earthquakes, routine wear, neglect, and many maintenance problems are commonly excluded.
- Your deductible, coverage limits, and valuation method affect how much a successful claim pays.
- Endorsements or separate policies can close gaps for floods, earthquakes, sewer backups, valuables, and added liability.
What Does Homeowners Insurance Cover in a Standard Policy?
The National Association of Insurance Commissioners identifies six common coverage areas in home policies. They protect property, belongings, living expenses, liability, and certain medical expenses. Exact protections still differ by company, policy form, and state.
Coverage also depends on how the policy treats the cause, often called a peril. Some property is covered unless the policy specifically excludes the cause. Other coverage may apply only to causes named within the contract.
Dwelling and Other Structures Coverage
Dwelling coverage protects the physical house and items permanently attached to it. That usually includes walls, floors, roofing, built-in fixtures, and attached structures. Your limit should reflect rebuilding costs, not the home’s sale price.
Other structures coverage can protect detached property such as sheds, fences, and detached garages. Its limit is often tied to the dwelling coverage amount. Triple-I notes that many policies set this coverage near 10% of the dwelling amount.
Roof maintenance still matters because insurance is not a substitute for normal upkeep. Homlyst’s asphalt shingle roof cost and maintenance guide can help with planning roof work. Keeping records of inspections and repairs can also help document a home’s condition.
Personal Property Coverage
Personal property coverage protects belongings such as furniture, clothing, electronics, and household goods. Covered theft may extend to belongings taken away from your home. Special limits can apply to jewelry, artwork, collectibles, cash, and other valuable property.
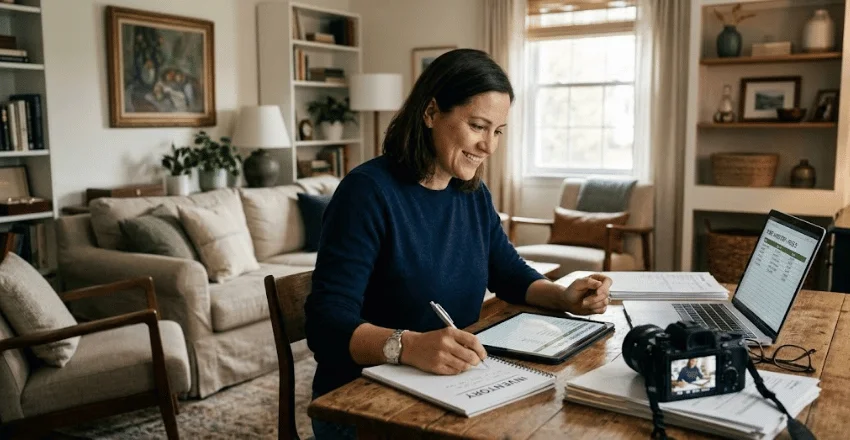
Triple-I says personal belongings coverage is commonly set between 50% and 70% of dwelling coverage. That percentage may not match what your household owns. A detailed home inventory provides a better way to check whether your limit is sufficient.
Personal Liability and Medical Payments
Personal liability coverage can help when you are legally responsible for another person’s injury or property damage. It may also help pay defense costs when a covered claim becomes a lawsuit. The policy only pays up to its stated liability limit.
Medical payments coverage handles certain smaller injuries involving people outside your household. It can sometimes pay without first establishing legal responsibility. It generally does not pay your own household’s medical expenses.
Loss-of-Use Coverage
A serious covered loss can make a house temporarily unlivable during repairs. Loss-of-use coverage can help with added hotel, rental, meal, and related living expenses. These payments apply only when the underlying damage qualifies under the policy.
This protection does not mean every cost while living elsewhere gets reimbursed. Policies can impose dollar limits, time limits, or rules about reasonable added expenses. Keep receipts and ask your carrier how expenses must be documented.
Which Events Are Usually Covered?
Common policy perils include fire, lightning, wind, hail, smoke, theft, vandalism, and certain sudden water events. The exact list depends on the form and any attached exclusions. NAIC recommends reading the contract because policies can define covered causes differently.
| Situation | Usually covered? | Why |
|---|---|---|
| House fire | Often | Fire is a standard covered peril |
| Wind or hail damage | Often | Common covered weather events |
| Burst interior pipe | Often | Sudden accidental water damage may qualify |
| Theft | Often | Personal property protection commonly includes theft |
| Storm drops tree onto house | Often | Resulting structural damage may qualify |
| Outside flood | Usually no | Separate flood protection is generally required |
| Earthquake | Usually no | Separate coverage or endorsement is commonly needed |
| Old roof wearing out | Usually no | Wear and maintenance are not insured accidents |
| Sewer or drain backup | Usually no | Often requires an endorsement |
A storm-damaged tree can create both repair and cleanup questions. Homlyst’s tree removal cost guide explains common removal considerations for homeowners. Claim coverage still depends on what the tree damaged and what caused it to fall.
What Home Insurance Usually Doesn’t Cover
Standard protection does not cover every expensive problem a homeowner may face. Floods, earthquakes, routine deterioration, and neglect commonly fall outside ordinary coverage. Sewer backups and some ground movement risks may also require added protection.
Flooding deserves special attention because ordinary home policies generally exclude it. The National Flood Insurance Program states that most home policies do not cover flood damage. When eligible, property owners can obtain separate flood protection.
Maintenance-related moisture problems can also become costly without creating a valid claim. Homlyst’s basement waterproofing guide covers ways homeowners can address recurring moisture risks. Preventing gradual damage is different from insuring a sudden accidental event.
Does Home Insurance Cover Water Damage?
Sudden and accidental water damage often receives different treatment from gradual water problems. A pipe that suddenly bursts may qualify under dwelling or personal property coverage. A slow leak caused by neglected maintenance is much less likely to qualify.
Water entering from an outside flood is another category entirely. Standard policies generally exclude flooding from rising surface water or storm surge. Sewer and sump-pump backups also commonly need specific added coverage.
Routine maintenance can reduce the chance that a small problem develops over months. Homlyst’s preventative plumbing maintenance guide covers leaks, water heaters, drains, and seasonal checks. Keep repair records when addressing recurring plumbing issues.
Does Home Insurance Cover Roof Damage?
Roof coverage usually depends on what caused the damage, not the repair cost alone. Wind, hail, fire, or a falling tree may create a covered dwelling claim. Damage from age, deterioration, or neglected maintenance is generally excluded.
The same distinction can apply when damaged roofing allows rain into the house. Water entering through sudden storm damage may qualify with the roof repair. Water entering through an old, deteriorated roof may not receive the same treatment.
Does Home Insurance Cover Theft?
Theft is commonly included within personal property protection. A covered claim can reimburse stolen belongings up to applicable limits and after the deductible. Damage caused during a break-in may fall under dwelling or other-structures protection.
Some belongings can have lower special limits than your general contents limit. Jewelry, collections, and similar valuables may need scheduled coverage for stronger protection. Keep receipts, appraisals, serial numbers, and photographs for items with meaningful value.
How Deductibles, Limits, and Valuation Affect a Claim
Having a covered loss does not mean the insurer pays every repair dollar. The deductible represents the portion of a covered property loss you must absorb. Policy limits set the maximum amount available for each coverage category.
Valuation also affects how damaged property is paid. Replacement-cost coverage focuses on replacing covered property without the same depreciation deduction used by actual-cash-value coverage. Review which method applies to your dwelling and belongings before a claim happens.
Your dwelling limit should reflect the estimated cost to rebuild the structure. That amount can differ significantly from the property’s real estate market value. Labor, materials, building requirements, and reconstruction conditions can all influence rebuilding costs.
Extra Coverage You May Need
You can often expand a standard contract through endorsements or separate policies. Which additions matter depends on your location, valuables, property features, and financial exposure. Review likely risks rather than assuming the base package covers everything.
| Additional protection | What it can address |
|---|---|
| Flood insurance | Flooding excluded from most standard policies |
| Earthquake coverage | Earth movement excluded from many standard policies |
| Water-backup endorsement | Sewer, drain, or sump-pump backup losses |
| Scheduled valuables | Higher protection for jewelry, art, or collectibles |
| Umbrella liability | Liability exposure beyond underlying policy limits |
Flood and earthquake protection may be especially important where local hazards are significant. Water-backup protection can address a gap that owners sometimes discover only after damage occurs. Higher liability limits can matter when you have substantial assets to protect.
How to Review Your Policy Before You Need It
Start with the declarations page and identify every listed coverage limit. Check the property deductible and any separate wind, hail, or catastrophe deductible. Then read exclusions and endorsements that change the standard wording.
Next, compare your dwelling limit with a current rebuilding estimate. Create or update a room-by-room inventory of your belongings. Ask whether valuable items need separate scheduling or appraisal documentation.
Review the policy again after renovations, major purchases, or property changes. New additions can change rebuilding costs and create different risks. Your insurer or licensed agent can explain how your specific state and contract affect coverage.
Frequently Asked Questions
What does homeowners insurance cover?
A standard policy commonly protects your dwelling, detached structures, belongings, liability, guest medical expenses, and certain added living costs. Payment applies only when the cause qualifies under the contract. Limits, deductibles, and exclusions can reduce or prevent reimbursement.
Does a policy cover a broken appliance?
A policy may cover resulting damage if an appliance suddenly causes a covered accident. It usually does not replace an appliance that fails through ordinary wear. Equipment-breakdown endorsements can provide different protection depending on the insurer.
Is flood damage covered?
Most standard home policies do not cover flood damage. Separate flood insurance is designed for that exposure. NFIP coverage is available in participating communities subject to program rules.
How much dwelling coverage do I need?
The dwelling limit should generally reflect the cost to rebuild the insured structure. It should not be based only on the home’s current sale price. Ask for an updated reconstruction estimate when building costs rise or the home changes.
Does a policy cover a guest who gets injured?
Personal liability may respond when you are legally responsible for a covered injury. Medical-payments coverage can address certain smaller guest injuries without establishing fault. Limits and exclusions still determine how much protection applies.
Know the Cause Before You Assume You’re Covered
The key question after property damage is often not what broke but why it broke. Sudden insured events are treated differently than deterioration, neglect, flooding, or other exclusions. Reading that distinction before a loss can prevent expensive surprises.
Review your declarations page, exclusions, deductibles, and endorsements before your next renewal. Update your home inventory and rebuilding estimate at the same time. Ask your insurer for written clarification when any important risk remains unclear.